DeFi Borrow RatesBorrowing dollars in DeFi costs about 7.2% a year, roughly three points more than the Fed
Variable rates for borrowing stablecoins, ETH and BTC across the biggest DeFi lending markets, with rewards paid to borrowers separated from interest. Lenders in the same USDC markets earn about 7.0%, 0.3 points less: part of the interest goes to the protocol, and not every dollar supplied is lent out.
Weighted by the $7.8B borrowed across 144 markets.
Ethereum: $2.2B borrowed, 98% of what’s lent. Rates climb steeply when a market is nearly fully lent.
Arbitrum.
Borrow rates by market
Variable rates for borrowing each asset, by lending market. Isolated markets lend only against the collateral named.
Borrow APY = interest less any token rewards paid to borrowers. Sort by any column.
112 rows shown
| WETH · Aave V3Ethereum | 1.93% | 1.93% | – | $4.0B | |
|---|---|---|---|---|---|
| USDT · Aave V3Ethereum | 4.40% | 4.40% | – | $2.5B | |
| USDC · Aave V3Ethereum | 11.20% | 11.20% | – | $2.2B | |
| USDC · Morpho BlueBase · against CBBTC | 5.37% | 5.37% | – | $1.6B | |
| WETH · SparkLendEthereum | 1.88% | 1.88% | – | $1.2B | |
| USDS · SparkLendEthereum | 4.32% | 4.32% | – | $891M | |
| USDT0 · Aave V3Plasma | 4.40% | 4.40% | – | $738M | |
| USDC · Hyperliquid EarnHyperliquid L1 | 5.00% | 5.00% | – | $438M | |
| UZR · FiraEthereum · Max leverage ~10.09x | 0.00% | 0.00% | – | $435M | |
| USDC · Morpho BlueBase · against USDE | 4.58% | 4.58% | – | $340M | |
| USDC · Compound V3Ethereum | 3.95% | 3.95% | – | $339M | |
| USDG · Morpho BlueRobinhood Chain · against USDE | 5.03% | 5.03% | – | $323M | |
| USDC · Morpho BlueEthereum · against CBBTC | 5.01% | 5.01% | – | $308M | |
| USDT · SparkLendEthereum | 3.94% | 3.94% | – | $306M | |
| USD1 · DolomiteEthereum | 5.63% | 5.63% | – | $268M | |
| USDE · Jupiter LendSolana · USDe/PYUSD (Sentora Market) | 4.55% | 4.55% | – | $242M | |
| RLUSD · Morpho BlueEthereum · against KBTC | 9.10% | 9.10% | – | $240M | |
| SOL · Kamino LendSolana · SOL/BTC Market | 6.46% | 6.46% | – | $223M | |
| DAI · SparkLendEthereum | 4.43% | 4.43% | – | $189M | |
| PYUSD · Morpho BlueEthereum · against PRIME | 5.15% | 5.15% | – | $186M | |
| DAI · Sky LendingEthereum · ETH-A · against WETH | 10.50% | 10.50% | – | $181M | |
| WETH · Aave V3Base | 2.01% | 2.01% | – | $178M | |
| DAI · Sky LendingEthereum · ETH-C · against WETH | 10.25% | 10.25% | – | $177M | |
| JLP · Jupiter LendSolana · JLP/USDC | 7.05% | 7.05% | – | $176M | |
| USDC · Aave V3Base | 5.65% | 5.65% | – | $176M | |
| USDC · Aave V3Arbitrum | 3.51% | 3.51% | – | $169M | |
| USDS · Sky LendingEthereum · SKY Staking Engine · against SKY | 7.41% | 7.41% | – | $162M | |
| USDC · Aave V3Monad | 5.18% | 5.18% | – | $158M | |
| USDT0 · Aave V3Mantle | 3.68% | 3.68% | – | $148M | |
| USDT · Compound V3Ethereum | 4.73% | 4.73% | – | $144M | |
| USDT · JustLend V1Tron | 4.07% | 4.07% | – | $144M | |
| ETH · Fluid LendingEthereum · against WSTETH | 2.11% | 2.11% | – | $141M | |
| USDT · Venus Core PoolBSC | 5.15% | 5.15% | – | $136M | |
| USDT · Morpho BlueEthereum · against WSTETH | 6.12% | 6.12% | – | $135M | |
| WETH · Aave V3Arbitrum | 1.94% | 1.94% | – | $129M | |
| USDC · Morpho BlueEthereum · against PT-REUSD-10DEC2026 | 10.21% | 10.21% | – | $126M | |
| USDG · Morpho BlueRobinhood Chain · against SYRUPUSDG | 4.87% | 4.87% | – | $122M | |
| USDC · Kamino LendSolana · SOL/BTC Market | 5.89% | 5.89% | – | $120M | |
| DAI · Aave V3Ethereum | 5.01% | 5.01% | – | $118M | |
| USDC · Morpho BlueEthereum · against WBTC | 5.16% | 5.16% | – | $115M | |
| PYUSD · Morpho BlueEthereum · against KBTC | 4.20% | 4.20% | – | $114M | |
| USDC · DolomiteEthereum | 5.06% | 5.06% | – | $109M | |
| GHO · Aave V3Ethereum · against GHO | 4.50% | 4.50% | – | $107M | |
| WHYPE · HyperLend PooledHyperliquid L1 | 1.00% | 1.00% | – | $103M | |
| BTCB · Venus Core PoolBSC | 1.09% | 1.09% | – | $100M | |
| RLUSD · Aave V3Ethereum · Aave Horizon Market | 3.41% | 3.41% | – | $99M | |
| PYUSD · Morpho BlueEthereum · against SUSDE | 4.12% | 4.12% | – | $98M | |
| USDC · Morpho BlueBase · against WETH | 5.37% | 5.37% | – | $97M | |
| ETH · Compound V3Ethereum | 1.94% | 1.94% | – | $93M | |
| USDG · Morpho BlueArbitrum · against SYRUPUSDG | 3.04% | 3.04% | – | $92M | |
| RLUSD · Morpho BlueEthereum · against WEETH | 10.95% | 10.95% | – | $90M | |
| DFDVSOL · Jupiter LendSolana · dfdvSOL/WSOL | 5.15% | 5.15% | – | $84M | |
| USDT · Morpho BlueEthereum · against WBTC | 6.12% | 6.12% | – | $84M | |
| JUPSOL · Jupiter LendSolana · JupSOL/USDC | 7.05% | 7.05% | – | $74M | |
| WSOL · Jupiter LendSolana · WSOL/USDC | 7.05% | 7.05% | – | $72M | |
| USDC · Aave V3Avalanche | 7.63% | 7.63% | – | $64M | |
| PYUSD · Morpho BlueEthereum · against PST | 6.52% | 6.52% | – | $64M | |
| USDC · Kamino LendSolana · OnRe Market | 7.41% | 7.74% | 0.33% | $64M | |
| USDT0 · Aave V3Monad | 4.64% | 4.64% | – | $63M | |
| USDC · Morpho BlueBase · against CBXRP | 6.82% | 6.82% | – | $59M | |
| TRX · JustLend V1Tron | 4.27% | 4.27% | – | $58M | |
| WBTC · Aave V3Ethereum | 0.32% | 0.32% | – | $57M | |
| USDT · Morpho BlueEthereum · against SUSDS | 5.95% | 5.95% | – | $56M | |
| WETH · Morpho BlueEthereum · against WSTETH | 1.93% | 1.93% | – | $55M | |
| PYUSD · Morpho BlueEthereum · against SYRUPUSDC | 4.45% | 4.45% | – | $55M | |
| JUPSOL · Jupiter LendSolana · JupSOL/WSOL | 5.15% | 5.15% | – | $55M | |
| WAVAX · Aave V3Avalanche | 3.19% | 3.19% | – | $53M | |
| USDT · Aave V3BSC | 4.08% | 4.08% | – | $53M | |
| SUSDAI · Jupiter LendSolana · sUSDai/USDC | 5.98% | 5.98% | – | $53M | |
| RLUSD · Morpho BlueEthereum · against USDE | -0.98% | 4.02% | 5.00% | $52M | |
| USDC · TydroInk | 6.30% | 6.30% | – | $50M | |
| INF · Jupiter LendSolana · INF/WSOL | 5.15% | 5.15% | – | $49M | |
| USDC · HyperLend PooledHyperliquid L1 | 6.82% | 6.82% | – | $47M | |
| USDC · Morpho BlueEthereum · against WEETH | 6.62% | 6.62% | – | $47M | |
| USDC · SparkLendEthereum | 4.36% | 4.36% | – | $45M | |
| PYUSD · Kamino LendSolana · Maple Market | 3.79% | 3.79% | – | $44M | |
| USDC · Morpho BlueBase · against MGLO | 5.55% | 5.55% | – | $43M | |
| DOLA · Inverse Finance FiRMEthereum · Fixed Borrow Rate · against DOLA-SUSDE | 4.64% | 4.64% | – | $42M | |
| WSTETH · Aave V3Ethereum · Prime Instance | 0.17% | 0.17% | – | $41M | |
| USDG · Kamino LendSolana · SOL/BTC Market | 6.13% | 6.13% | – | $41M | |
| WBNB · Venus Core PoolBSC | 0.30% | 0.30% | – | $40M | |
| USDC · Blend Pools V2Stellar · Fixed Pool | 10.13% | 10.13% | – | $39M | |
| GHO · Aave V3Ethereum · Prime Instance | 3.97% | 3.97% | – | $39M | |
| USD₮0 · Aave V3Arbitrum | 4.05% | 4.05% | – | $39M | |
| USDC · CurrentSui · MainMarket | 4.14% | 4.14% | – | $37M | |
| WETH · Aave V3Ethereum · Prime Instance | 1.92% | 1.92% | – | $37M | |
| WSTETH · Aave V3Ethereum | 0.02% | 0.02% | – | $34M | |
| USD₮0 · Aave V3Xlayer | 3.68% | 3.68% | – | $33M | |
| USDC · Morpho BlueMonad · against AHYPER | 7.70% | 7.70% | – | $32M | |
| MUSD · Aave V3Monad | 4.93% | 4.93% | – | $31M | |
| USDT · Fluid LendingEthereum · against ETH | 5.75% | 5.75% | – | $30M | |
| USDC · Kamino LendSolana · Figure Market | 5.70% | 5.70% | – | $30M | |
| USDG · Morpho BlueRobinhood Chain · against MGLO | 5.50% | 5.50% | – | $30M | |
| WSRUSD · CurvanceMonad · wsrUSD/USDC | 5.53% | 5.53% | – | $30M | |
| USDE · Aave V3Plasma | 6.61% | 6.61% | – | $30M | |
| USDC · Venus Core PoolBSC | 5.83% | 5.83% | – | $30M | |
| USDC · Morpho BlueEthereum · against WSTETH | 5.03% | 5.03% | – | $30M | |
| USDC · Morpho BlueEthereum · against PST | 9.99% | 9.99% | – | $30M | |
| EURC · Aave V3Ethereum | 3.98% | 3.98% | – | $29M | |
| USDC · Morpho BlueMonad · against PT-USDAT-14JAN2027 | 9.73% | 9.73% | – | $29M | |
| USDC · Fluid LendingEthereum · against ETH | 7.40% | 7.40% | – | $28M | |
| PYUSD · Kamino LendSolana · SOL/BTC Market | 6.54% | 6.54% | – | $28M | |
| USDC · Fluid LendingArbitrum · against SUSDAI | 5.56% | 5.56% | – | $27M | |
| USDT0 · Fluid LendingArbitrum · against SUSDAI | 5.64% | 5.64% | – | $27M | |
| PST · Jupiter LendSolana · PST/JupUSD | 7.21% | 7.21% | – | $27M | |
| USDC · Morpho BlueEthereum · against WFALCONX | 6.77% | 6.77% | – | $26M | |
| PYUSD · Kamino LendSolana · Ethena Market | 4.99% | 4.99% | – | $26M | |
| LUSD · Liquity V1Ethereum · against ETH | 0.50% | 0.50% | – | $26M | |
| USDC · Morpho BlueEthereum · against FXSAVE | 6.33% | 6.33% | – | $26M | |
| CRVUSD · Curve LlamaLendEthereum · crvUSD borrow · against SREUSD | 0.99% | 0.99% | – | $24M | |
| RLUSD · Morpho BlueEthereum · against WBTC | 4.77% | 4.77% | – | $24M | |
| USDC · Morpho BlueEthereum · against PT-USD3-17DEC2026 | 11.21% | 11.21% | – | $24M | |
| WETH · Morpho BlueMonad · against WSTETH | 1.74% | 1.74% | – | $24M | |
| USDC · NAVI LendingSui | 8.84% | 8.84% | – | $24M | |
| CRVUSD · crvUSDEthereum · against WSTETH | 3.58% | 3.58% | – | $23M | |
| GHO · Fluid LendingEthereum · against REUSD | 6.05% | 6.05% | – | $23M | |
| USDC · Morpho BlueEthereum · against MF-ONE | 7.93% | 7.93% | – | $23M | |
| USDSUI · CurrentSui · MainMarket | 4.95% | 4.95% | – | $23M | |
| PST · Jupiter LendSolana · PST/USDC | 7.69% | 7.69% | – | $22M | |
| USDT · Aave V3Avalanche | 4.07% | 4.07% | – | $22M | |
| USDG · Kamino LendSolana · OnRe Market | 7.05% | 8.83% | 1.78% | $22M | |
| USDT0 · Aave V3Polygon | 6.78% | 6.78% | – | $22M | |
| PYUSD · Kamino LendSolana · Figure Market | 5.46% | 5.46% | – | $21M | |
| BOLD · Liquity V2Ethereum · against WSTETH | 2.50% | 2.50% | – | $21M | |
| USDT · Fluid LendingEthereum · against SUSDAI | 5.75% | 5.75% | – | $21M | |
| WETH · Euler V2Monad · EVK Vault eWETH-7 | 1.77% | 1.77% | – | $21M | |
| USDC · Morpho BlueEthereum · against USPC | 6.78% | 6.78% | – | $21M | |
| CASH · Kamino LendSolana · Figure Market | 5.06% | 5.06% | – | $21M | |
| RLUSD · SparkLendEthereum | 3.94% | 3.94% | – | $20M | |
| CRVUSD · crvUSDEthereum · against WBTC | 3.58% | 3.58% | – | $20M | |
| USDC · Morpho BlueEthereum · against USD3 | 11.02% | 11.02% | – | $20M | |
| PYUSD · SparkLendEthereum | 4.15% | 4.15% | – | $20M | |
| WYLDS · Kamino LendSolana · AUTO Market | 6.00% | 6.00% | – | $20M | |
| WETH · DolomiteEthereum | 1.56% | 1.56% | – | $20M | |
| USDC · Kamino LendSolana · Huma Market | 7.01% | 7.01% | – | $20M | |
| USDC · Kamino LendSolana · JLP Market | 9.32% | 9.32% | – | $20M | |
| SBTC · Zest V2Stacks | 1.49% | 1.49% | – | $20M | |
| SUI · NAVI LendingSui | 2.72% | 2.72% | – | $20M | |
| U · Venus Core PoolBSC | 3.70% | 3.70% | – | $19M | |
| ETH · Venus Core PoolBSC | 1.26% | 1.26% | – | $19M | |
| WSRUSD · CurvanceMonad · wsrUSD/AUSD | 5.54% | 5.54% | – | $19M | |
| WETH · Morpho BlueEthereum · against WSTETH | 1.91% | 1.91% | – | $18M | |
| DAI · Sky LendingEthereum · WSTETH-A · against WSTETH | 11.50% | 11.50% | – | $18M | |
| USDC · Aave V3Polygon | 6.61% | 6.61% | – | $18M | |
| CBBTC · SparkLendEthereum | 0.08% | 0.08% | – | $18M | |
| USDT · Flux FinanceEthereum | 4.95% | 4.95% | – | $17M | |
| SOL · Kamino LendSolana · Jito Market | 5.75% | 5.75% | – | $17M | |
| USDC · SaveSolana · Main Pool | 6.90% | 6.90% | – | $17M | |
| CRVUSD · Curve LlamaLendEthereum · crvUSD borrow · against SFRXUSD | 4.07% | 4.07% | – | $17M | |
| GHO · Aave V3Plasma | 4.16% | 4.16% | – | $17M | |
Source: DefiLlama (lending markets), observed .
USDC borrow rates across the biggest markets
Every USDC market with more than $100M borrowed, against the weighted average and the Fed funds midpoint.
DeFi lending protocols let you borrow against crypto you already hold, without selling it and without a credit check: you deposit collateral, borrow up to a set share of its value, and pay a variable rate set by how much of each market is already lent out. The tables above show what every major market charges right now; the guide below explains how those rates work and what can go wrong. Looking to earn instead? See DeFi lending rates.
How DeFi borrowing works, and what the risks are
What is DeFi borrowing?
A DeFi loan comes from a smart contract, not a company. Lenders deposit assets into a pool, borrowers lock up collateral and draw from it, and the contract sets the rate, tracks every position and liquidates any loan whose collateral falls too far. There’s no application, no identity check and no fixed term: you repay whenever you like, and interest accrues every block until you do.
Almost every DeFi loan is overcollateralized: you deposit more than you borrow. That’s what lets the contract lend to anyone, and it’s why DeFi borrowing is mostly used to unlock cash from crypto you want to keep, or to build leverage, rather than to fund spending you can’t cover.
How a DeFi loan works
- Connect a wallet on the network the market runs on (Ethereum, Base, Arbitrum, Solana and others).
- Deposit collateral, such as ETH, a BTC token like WBTC or cbBTC, or a stablecoin.
- Borrow up to the market’s maximum loan-to-value (LTV): at a 75% LTV, $10,000 of collateral supports up to $7,500 of debt.
- Watch your health factor. If the collateral’s value falls until the loan passes the liquidation threshold, anyone can repay part of your debt and take some of your collateral at a discount.
- Repay the debt plus interest to withdraw your collateral.
Borrowing well below the maximum is the main protection: the further your LTV sits from the liquidation threshold, the bigger a price drop your loan can take.
Why people borrow crypto
Cash without selling. Borrowing stablecoins against ETH or BTC gives you dollars to spend or deploy while keeping your position, and in the US a loan generally isn’t a sale, so it doesn’t realize a gain the way selling would (see crypto taxes).
Leverage. Borrow stablecoins against ETH, buy more ETH, and your exposure grows: so do your losses if the price falls, and the liquidation price moves closer.
Shorting and hedging. Borrowing an asset and selling it bets on its price falling; you buy it back later to repay.
Yield strategies. Some borrowers loop a liquid staking token against ETH to earn the staking yield on more ETH than they own, which only pays while the staking yield beats the borrow rate.
DeFi borrowing protocols
Aave is the largest lending protocol, on Ethereum and a dozen other networks. One pool per network lends stablecoins, ETH, liquid staking tokens and major DeFi tokens against a wide range of collateral, and it runs its own stablecoin, GHO.
Sky (formerly MakerDAO) lets you mint USDS, the successor to DAI, against collateral at a stability fee its governance sets. Spark, built within the Sky ecosystem, runs SparkLend, an Aave-style market that draws on Sky’s stablecoin liquidity.
Compound v3 splits lending into markets that each lend a single asset, such as USDC or ETH, against a set list of collateral.
Morpho hosts isolated markets, each one collateral and one loan asset with its own terms, so a problem in one market doesn’t spread to the others. It powers Coinbase’s bitcoin-backed loans.
Kamino is the largest lending protocol on Solana, with markets for SOL, its liquid staking tokens and stablecoins.
Curve’s crvUSD and Liquity mint their own stablecoins against collateral instead of lending from a pool; crvUSD sells collateral gradually as prices fall (soft liquidation) rather than all at once.
How borrow rates are set, and what you actually pay
Most pools set the rate from utilization, the share of deposits already lent out. The rate rises slowly until utilization reaches a target, then steeply above it, which pulls in lenders and pushes out borrowers. That’s why a nearly fully lent market can cost several times the average, and why a rate can jump overnight.
Some markets pay borrowers token rewards. The table’s Borrow APY is interest less those rewards; rewards are paid in the protocol’s own token, can end at any time, and are worth only what the token sells for. Compare the Interest column to see what you’d pay without them.
Rates are variable and quoted as an annual rate. You also pay network fees to open, adjust and close a loan, which matter more on Ethereum mainnet than on Base, Arbitrum or Solana.
Risks of DeFi borrowing
Liquidation. A sharp fall in your collateral’s price can trigger liquidation within minutes, and you lose the liquidation penalty on top. Markets moving fast and congested networks make it hard to add collateral in time.
Rate spikes. A variable rate can climb quickly when a market fills up; a loan that was cheap last week can cost far more today.
Smart contract risk. A bug or exploit can drain a pool. Audits and bug bounties reduce the risk but don’t remove it.
Oracle risk. Protocols price collateral from oracles; a faulty or manipulated price can liquidate healthy loans or let attackers borrow against inflated collateral.
Stablecoin and collateral risk. If the stablecoin you borrowed or deposited loses its peg, or a token you posted collapses, the numbers your loan depends on change.
DeFi loans vs. crypto-backed loans from lenders
Companies such as Nexo, Ledn, Arch and Figure also lend against crypto, often at a fixed rate and a lower maximum LTV, and some lend dollars to your bank account. The trade-off is custody: the lender holds your collateral, so its solvency matters as much as its rate. We compare them, from each lender’s own site, on crypto lending platforms, and bitcoin-backed loans specifically on Bitcoin lending rates and ether-backed loans on Ethereum lending rates.
Flash loans
A flash loan needs no collateral because it’s borrowed and repaid inside a single transaction: if the money isn’t back by the end of it, the whole transaction reverses. They’re used for arbitrage, swapping the collateral behind a loan, and refinancing, and they take code to use. Aave charges a small fee; Morpho and Balancer charge none. Many of the largest DeFi exploits were funded with flash loans.
The largest DeFi lending exploits
- Beanstalk, $182 million (April 2022): a flash loan bought enough governance votes to pass a proposal sending the protocol’s funds to the attacker.
- Compound, $150 million at risk (October 2021): a bug in a protocol upgrade paid out excess COMP rewards.
- Cream Finance, $130 million (October 2021): a flash loan attack exploited how the protocol priced a collateral token.
- Mango Markets, $116 million (October 2022): a trader pushed up the price of the thinly traded MNGO token and borrowed against it.
- bZx, $55 million (November 2021): a stolen private key, not a contract bug.
The pattern: manipulated prices and governance, not just code bugs. Markets with deep, well-priced collateral and time-locked governance have held up best.
Questions
- What is a DeFi loan?
A loan from a smart contract: you deposit crypto as collateral and borrow against it, with no application or credit check. You repay whenever you like, and the contract liquidates the loan if your collateral’s value falls too far.
- Where is it cheapest to borrow USDC?
The spread chart above shows every USDC market with more than $100 million borrowed, and the table sorts every market by its rate. The cheapest large market changes often, since rates follow how much of each market is lent out.
- How much can I borrow against my crypto?
Up to the market’s maximum loan-to-value, which depends on the collateral: higher for ETH and BTC, lower for volatile tokens. Borrowing well below the maximum leaves room for the price to fall before liquidation.
- What happens if my collateral’s price falls?
Once your loan crosses the liquidation threshold, anyone can repay part of it and take some of your collateral at a discount. You keep the borrowed funds but lose that collateral and the liquidation penalty. Adding collateral or repaying part of the loan moves you back to safety.
- Is borrowing crypto a taxable event?
In the US, taking out a loan generally isn’t a sale, so it doesn’t realize a gain. A liquidation can be, since your collateral is sold. See crypto taxes and talk to a tax professional about your situation.
- What’s the difference between DeFi borrowing and a crypto-backed loan from a company?
In DeFi a smart contract holds your collateral and the rate is variable; a company holds your collateral itself, often with a fixed rate and a lower maximum LTV. Compare them on crypto lending platforms.
 Hyperliquid Policy Center Urges SEC to Adopt Crypto Rules with Five Changes
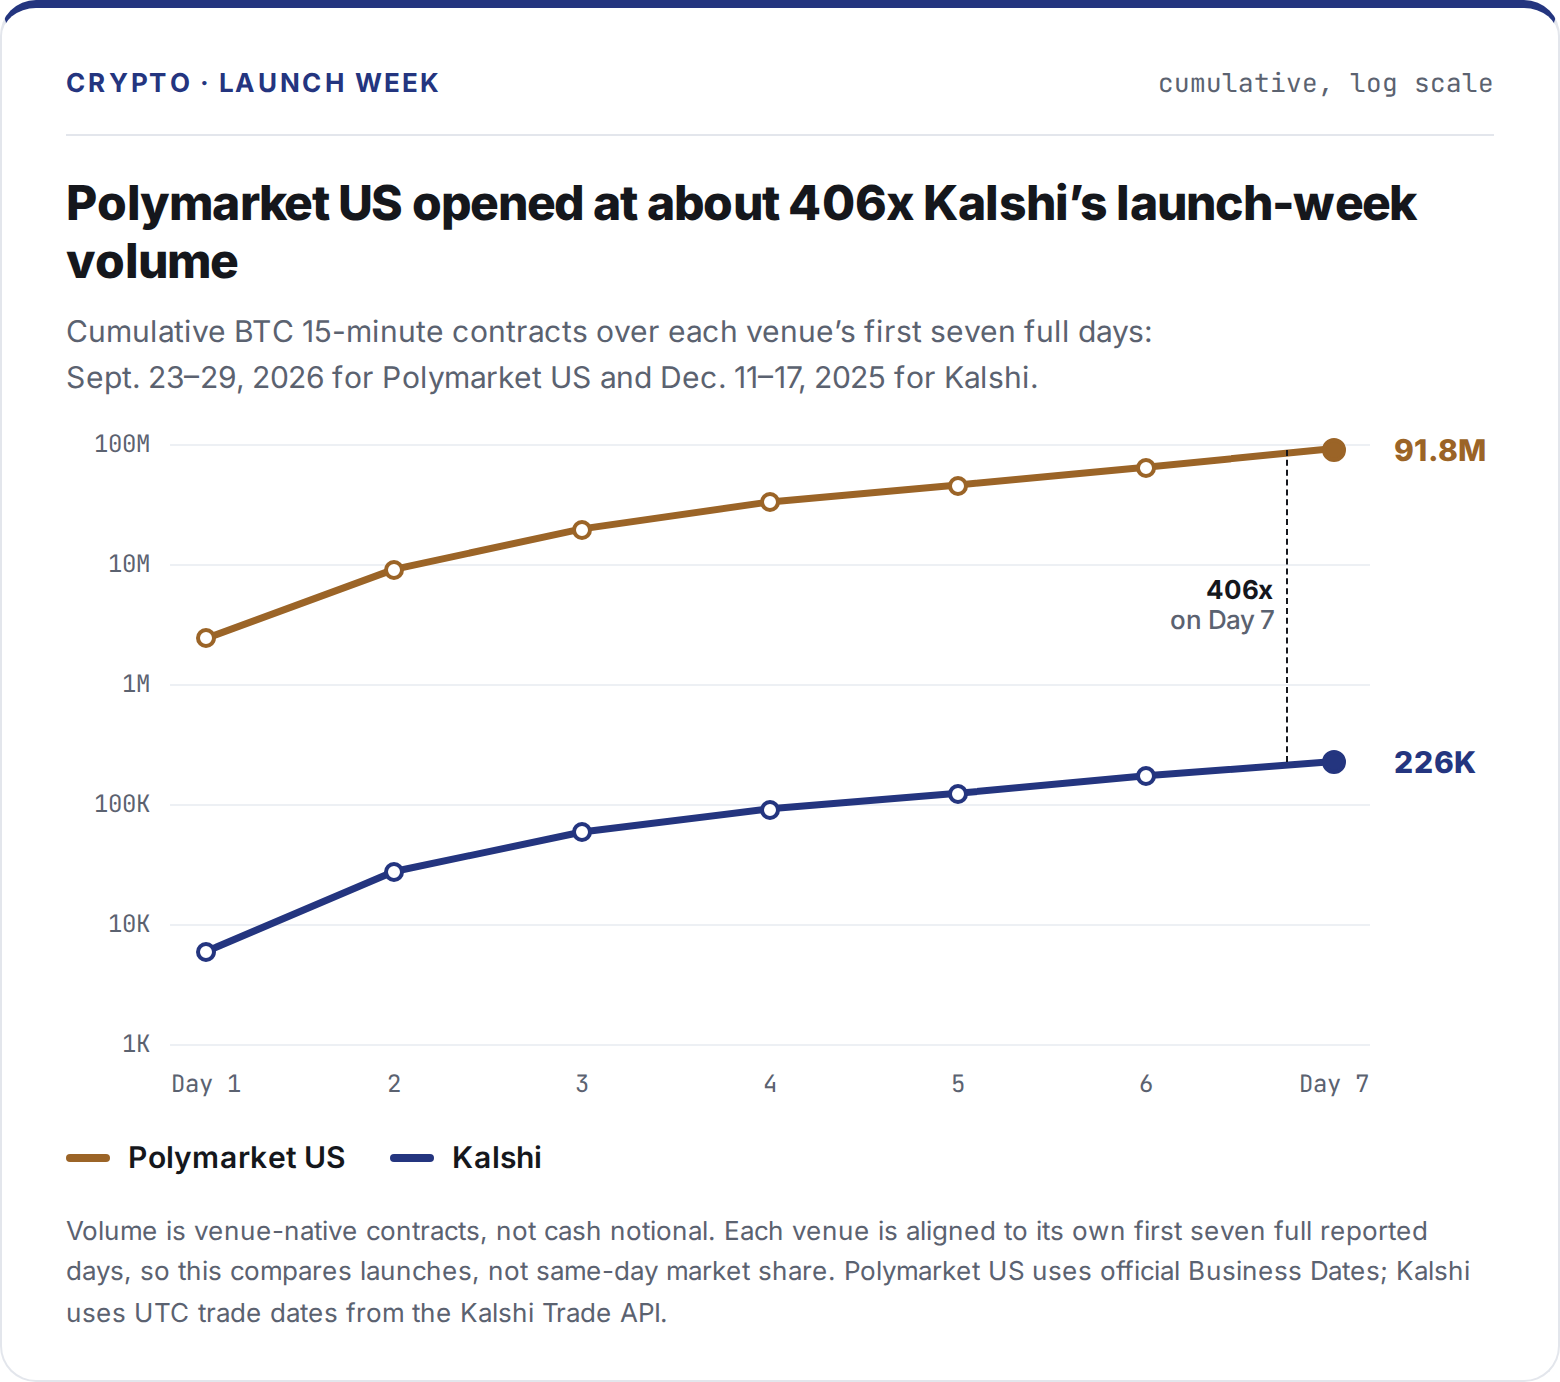 Polymarket US 15-Minute Bitcoin Volume Hits $92M in First Full Week
 SEC Issues Innovation Exemption as CLARITY Act Fails
 CZ Says IPOs Will Move On-Chain, Have They Not Already?